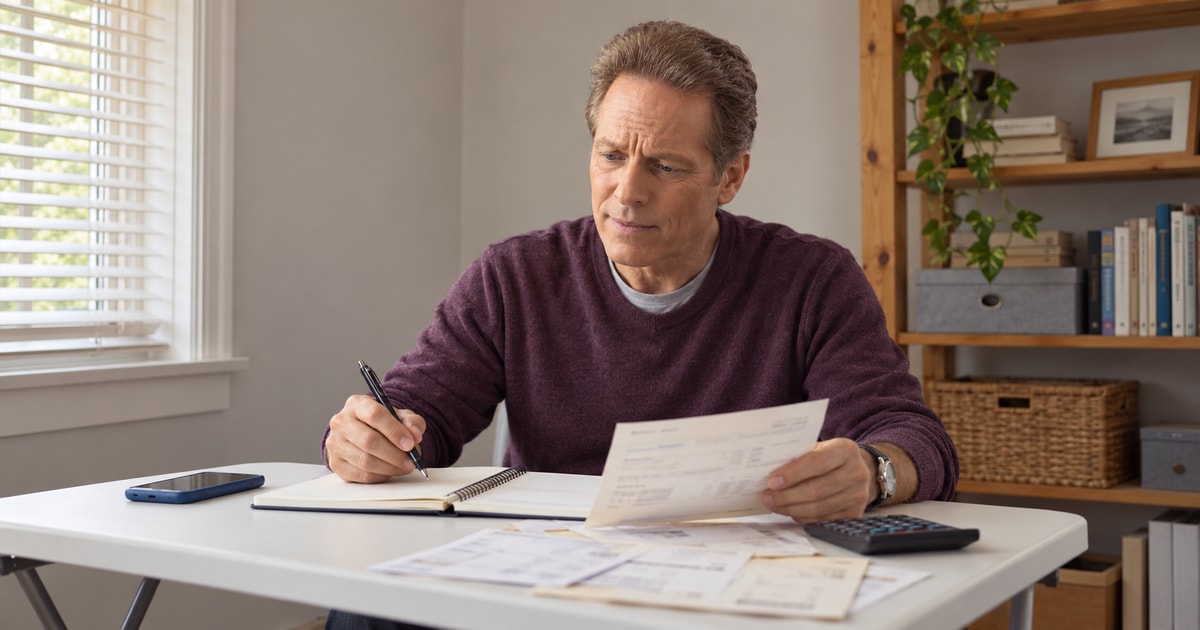
A money goal can be as practical as understanding the next bill, preparing for an expense or finding out what support is available. You do not have to begin with an investment or a promise of financial independence.
Start with your actual circumstances. A plan should help you see choices and questions—not shame you for having limited resources.
1. Describe the immediate need
Try: “I need to understand which bills fall before payday,” “I want to know what this training will cost,” or “I would like a reserve for an unexpected expense.”
Separate an urgent need from a longer-term hope. If you are at risk of losing essentials or facing a legal or financial deadline, seek suitable local help rather than assuming a savings habit will resolve the immediate problem.
2. Put the available information in one place
If it is safe to do so, list expected income, essential expenses, due dates and the terms of relevant accounts or debts. Mark estimates and unknowns rather than inventing a precise figure.
The US Consumer Financial Protection Bureau’s Your Money, Your Goals toolkit includes tools for tracking income and bills, considering debt and setting goals. Choose the parts that address your question rather than treating the whole toolkit as an assignment.
If money is controlled by someone who threatens or monitors you, consider appropriate individual safety support. Do not assume that opening an account or changing access secretly is safe in every situation.
3. Ask the question that fits the goal
| A goal | Information to clarify | A useful next question |
|---|---|---|
| Meet upcoming expenses | Amounts, due dates and available funds | Which issue needs attention first, and who can explain the options? |
| Prepare for an unexpected cost | Likely needs and access to support | What is a realistic starting point in my circumstances? |
| Understand debt | Balance, rate, fees and payment terms | Which qualified source can help compare my options? |
| Plan a purchase or course | Full cost, timing and ongoing expenses | What would I need to know before committing? |
4. Keep saving and investing distinct
An emergency reserve is intended for unexpected costs. The CFPB emergency-fund guide explains that an appropriate amount depends on your situation. There is no single target everyone must reach.
If you consider automatic transfers, check balances, timing and fees first. An arrangement that causes an overdraft is not automatically helpful because it is called saving.
Investing involves different risks. Investor.gov explains that stocks can lose value. Do not assume a dividend, a stock split or a small initial purchase guarantees growth. This article does not select investments or a repayment strategy for you.
5. Get advice for the actual decision
For debt, tax, benefits, insolvency, a mortgage or an investment decision, use a relevant qualified or official source for your location and circumstances. Check the person’s role, costs and any relationship that may affect their advice.
Before paying extra on a loan or choosing a debt strategy, understand the actual terms and how the decision fits your other needs. The smallest balance, the largest payment or a tax refund does not by itself identify the right choice for everyone.
If an arrangement is unaffordable, ask the relevant provider or support service what options may be available. Do not assume an informal promise changes the agreement; seek appropriate advice about unclear terms.
Keep spiritual reflection about values, not returns
A prayer, journal or reading can help you name what security, generosity or independence means to you. It cannot confirm an investment return, predict a windfall or make a fee necessary to attract money.
If readings are part of your discretionary spending, decide what you can afford before booking and keep essentials in view. You may pause spending without losing a spiritual opportunity.
Review when circumstances change
Ask what information is clearer, what changed and which next question matters now. A revised goal is not evidence that you lacked discipline.
There may be no easy expense to cut. Income, health, caring responsibilities and the cost of essentials can affect what is possible. A useful next step may be seeking support rather than trying harder at the same plan.
Questions about setting a financial goal
1. What counts as a financial goal?
It can be an immediate need, such as understanding a bill, or a longer-term aim. It does not have to involve investing or a large amount of money.
2. What information should I gather first?
If safe, gather relevant income, expenses, due dates and account or debt terms. Mark what you do not yet know and ask the appropriate source to clarify it.
3. What if my income changes from month to month?
Account for the uncertainty rather than assuming a fixed amount will always arrive. A suitable budgeting resource or qualified adviser can help explore your circumstances.
4. Is there one emergency savings target everyone needs?
No. Needs and available resources differ. A useful starting point depends on your circumstances, not a universal number.
5. Are automatic savings transfers always helpful?
Not automatically. Check the timing, available balance and fees, including possible overdraft costs. Review the arrangement when circumstances change.
6. Is buying a stock the same as building an emergency reserve?
No. Stocks involve investment risk and may lose value. Consider the purpose, access needs and risks of any money decision with appropriate guidance.
7. Does a dividend guarantee an investment will grow?
No. Do not treat a dividend or a stock split as a guaranteed return. Learn about the investment and its risks through qualified sources.
8. Should everyone repay the smallest debt first?
No single repayment order fits every circumstance. Rates, terms, essential needs and other factors may matter; seek qualified guidance suited to you.
9. Should I make an extra mortgage payment?
That depends on the actual terms and your wider circumstances. Ask a relevant qualified source before assuming it is the best use of available funds.
10. What if there are no easy expenses to cut?
That does not establish a failure of discipline. Consider relevant local support and advice about the actual shortfall and available options.
11. Can a psychic predict a winning investment?
A spiritual interpretation cannot establish a future return or replace investment research and qualified financial advice.
12. Do I need to pay for a ritual to attract money?
No. A fee is not a requirement for financial opportunity, and a ritual cannot guarantee income or a windfall.
13. How can I include readings in a spending plan?
Treat an optional reading as discretionary spending, check the full cost before booking and decide what is affordable after considering your needs. You can choose not to spend.
14. What if another person controls access to money?
If there are threats or monitoring, seek suitable individual safety support. A general financial checklist is not a tailored safety plan.
15. When should I review a goal?
Review it when information or circumstances change, or when a check-in would be useful. Adjusting the plan does not mean the goal or your effort was worthless.
It’s great to see practical tips on managing mortgage payments and using tax refunds wisely. This can significantly reduce long-term debt.
Planning for the next year is essential. This advice is especially useful for those dealing with significant life changes or considering future financial goals.
While the advice on budgeting is sound, more detail on how to create and stick to a budget would be beneficial for readers who are new to this.
The suggestion to use a tax refund to make an extra mortgage payment is insightful. However, it might not be viable for everyone depending on their financial situation.
Focusing on paying off credit card debt by starting with the smallest amount owed is a practical method. It feels more achievable and can build momentum.
The article provides a solid foundation for anyone looking to achieve financial stability. The emphasis on small, achievable goals is particularly pragmatic.
I appreciate the advice on budgeting and the detailed steps on managing credit card debt. It’s crucial to have a clear financial plan.
The advice to set goals, budget, and regularly check progress is fundamental. It’s good to see a comprehensive yet straightforward approach to financial independence.
Agree. Regularly reviewing financial goals ensures you stay on track and can adjust as necessary to meet changing circumstances.
Considering the needs versus wants dichotomy is essential for financial independence. It’s often overlooked but highly impactful.
Indeed, differentiating between needs and wants is key to maintaining financial discipline.
The discussion on distinguishing between needs and wants is vital. It’s often an overlooked aspect of financial planning but very important for long-term stability.
The article provides a sensible approach to achieving financial stability. Setting small, reasonable goals seems like a pragmatic way to start.
The article highlights the importance of setting a monthly budget and sticking to it. This is a foundational principle of personal finance.
Planning for the next year is a habit that can yield significant benefits. It forces you to assess your financial situation and make necessary adjustments.
The suggestion to make saving and investing priorities is very relevant. Even small savings can add up over time, contributing to long-term financial health.
The advice on prioritizing saving and investing is crucial. It’s important to understand that financial independence requires deliberate effort.
Absolutely, making consistent efforts in saving and investing can significantly improve one’s financial stability over time.
The emphasis on both saving and investing is crucial. It’s good to see a guide that doesn’t neglect the importance of long-term financial growth.